Contact Us

Don't See What You're Looking For? Contact us today!

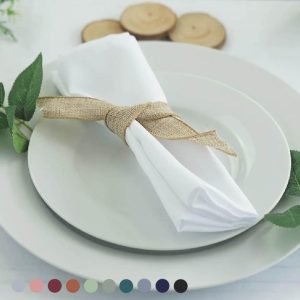
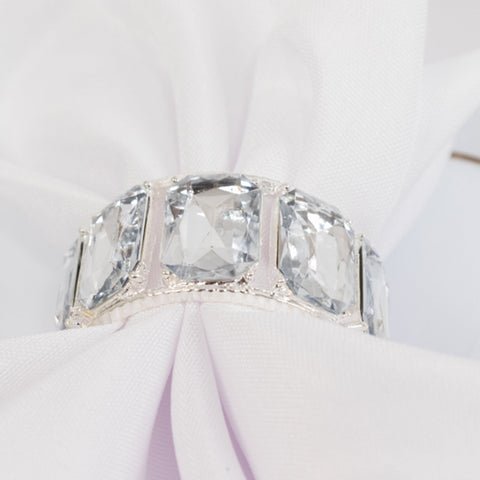
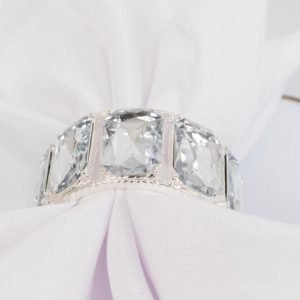
Diamond Gem Napkin Rings

$1.50

How Gift Cards Became a Trusted Payment Method in US Online Betting, According to Betzonic

The payment landscape for online betting in the United States has shifted considerably over the past decade, shaped by a combination of federal legislation, state-level regulation, and evolving consumer preferences. Among the methods that have carved out a legitimate and growing role in this ecosystem, gift cards stand out as a particularly interesting case. What began as a retail convenience product has evolved into a functional financial instrument that addresses specific friction points in the US online gambling market — friction that stems largely from banking restrictions that have no parallel in most other countries.

The Regulatory Context That Made Gift Cards Relevant

To understand why gift cards gained traction in US online betting, it is necessary to understand the Unlawful Internet Gambling Enforcement Act of 2006, commonly known as UIGEA. This federal law did not make online gambling illegal for players, but it prohibited US banks and payment processors from knowingly accepting transactions related to unlawful online gambling. The practical effect was significant: credit card companies like Visa and Mastercard began declining transactions directed at offshore betting operators, and even many domestic processors adopted conservative blanket policies to avoid compliance risk.

This created a persistent problem for players who wanted to fund accounts legally — particularly after the Supreme Court's 2018 decision in Murphy v. National Collegiate Athletic Association, which struck down the Professional and Amateur Sports Protection Act (PASPA) and opened the door for states to legalize sports betting. As legal, regulated sportsbooks launched in states like New Jersey, Pennsylvania, and Colorado, they still faced the reality that a meaningful percentage of attempted card transactions were declined at the processor level. The gap between legal activity and accessible payment infrastructure became a genuine operational challenge.

Gift cards, particularly those issued on the Visa and Mastercard networks, offered an indirect route around these declines. Because they are purchased at retail locations — grocery stores, pharmacies, convenience stores — the initial transaction is categorized as a retail purchase, not a gambling transaction. When the card is subsequently used at a betting site, the processor sees a prepaid card number rather than a direct bank transfer, which in many cases results in a higher approval rate. This structural characteristic, not any deliberate design for gambling, is what made them practically useful.

How the Gift Card Market Matured to Support Betting Use Cases

The integration of gift cards into online betting did not happen overnight, and it was not driven by the gambling industry alone. The broader prepaid card market in the United States grew substantially between 2010 and 2020, with the Consumer Financial Protection Bureau estimating that Americans loaded over $65 billion onto prepaid cards annually by the mid-2010s. As the infrastructure for these products matured — including better fraud detection, wider retail distribution, and higher load limits — their viability as a payment method for higher-value transactions improved correspondingly.

Several specific product categories became particularly relevant to bettors. Vanilla Visa and Mastercard gift cards, available in denominations up to $500 at most major retailers, became widely used. The OneVanilla and MyVanilla product lines, along with the Neosurf voucher system (which entered the US market from its European base), provided options at different price points and with varying acceptance rates across different operators. Neosurf, in particular, is notable because it was explicitly designed as an anonymous, cash-based voucher for online transactions, which aligned well with the preferences of privacy-conscious bettors.

Operators and review platforms began systematically tracking which gift card products worked at which sites, and which failed. Resources like www.betzonic.com/gift-card-betting-sites/ emerged to document exactly this kind of practical information — which operators accept specific card types, what the deposit limits are, and how the withdrawal process works in conjunction with gift card deposits. This type of aggregated, tested information became genuinely valuable because acceptance was inconsistent and players had no reliable way to know in advance whether a particular card would work at a particular site.

The withdrawal side of the equation remained more complicated. Gift cards are inherently a one-directional instrument — they can receive a load at purchase but cannot receive a bank transfer back from an operator in the way a debit card can. This meant that players using gift cards for deposits typically needed to select a different withdrawal method, most commonly a check by courier, a bank wire, or a cryptocurrency transfer. Operators that catered to gift card users generally developed clear policies around this asymmetry, and it became a standard feature of how the method was presented to customers.

Trust Signals and the Shift Toward Mainstream Acceptance

The question of trust is central to any payment method's adoption curve, and gift cards had specific obstacles to overcome in the betting context. Early use of prepaid cards in online gambling was associated with offshore, unlicensed operators, which created a reputational association that took years to reverse. As state-regulated markets expanded — by 2023, legal sports betting was available in more than 30 US states — the operators within those markets were subject to licensing requirements, responsible gambling mandates, and financial auditing that fundamentally changed the nature of the transaction.

Licensed operators in states like Michigan, Illinois, and Virginia had to meet strict requirements from their respective gaming control boards, including standards for payment processing transparency and anti-money laundering compliance. Accepting gift cards within this framework required operators to implement controls around maximum deposit limits, identity verification thresholds, and transaction monitoring. The result was that gift card use at licensed sites became a documented, auditable activity rather than an anonymous workaround — which paradoxically increased its legitimacy even while reducing some of the privacy characteristics that had originally attracted certain users.

Betzonic, which has tracked payment method developments across the US regulated market, has noted that the number of licensed operators explicitly advertising gift card acceptance grew substantially between 2020 and 2024. This visibility shift is meaningful: operators that list gift cards as an accepted method in their banking pages are making a deliberate commercial decision, not simply tolerating an edge case. It signals that the method has reached a sufficient volume of user demand to justify the compliance infrastructure required to support it properly.

Consumer trust was also reinforced by the dispute resolution mechanisms that came with regulated environments. A player using a gift card at a licensed New Jersey sportsbook, for example, had access to the Division of Gaming Enforcement as a regulatory backstop if a deposit was processed incorrectly or funds were disputed. This was categorically different from the situation facing players at offshore sites, where no such recourse existed. The combination of state licensing and consumer protection frameworks transformed the risk profile of gift card betting transactions in a way that made broader adoption rational rather than merely convenient.

Current Patterns and Practical Considerations for Users

As of the mid-2020s, gift card use in US online betting reflects a relatively stable set of patterns. The method is most commonly used by players who do not have a credit card that will process gambling transactions successfully, who prefer to manage their betting budget through a discrete, fixed-amount instrument, or who have privacy preferences that make direct bank connections unattractive. It is not a dominant payment method by transaction volume — ACH transfers, PayPal, and Play+ prepaid accounts hold larger shares at most major operators — but it occupies a consistent and identifiable niche.

Acceptance rates vary considerably by operator and by card product. Visa and Mastercard network gift cards tend to have higher acceptance rates at US-licensed sites than store-branded or single-retailer gift cards, which are generally not accepted for betting deposits at all. The denomination of the card can also affect processing: some operators apply different verification requirements to transactions above certain thresholds, which can complicate the use of higher-value cards. Players who use this method regularly typically develop practical knowledge about which specific products work reliably at their preferred operators, and this experiential knowledge is often shared in betting communities and review platforms.

Fees are a genuine consideration that is sometimes underweighted in discussions of gift card convenience. Most network-branded gift cards carry a purchase fee of $3.95 to $6.95 depending on the denomination and the retail outlet. For a $100 deposit, a $5.95 activation fee represents a 5.95% transaction cost — higher than most other payment methods available at licensed US sportsbooks. Players who use gift cards as a primary deposit method absorb these costs as a premium for the specific characteristics the method provides, whether that is privacy, budget control, or simply reliable transaction approval.

The trajectory of gift cards as a payment method in US online betting is ultimately a story about market adaptation. A product designed for retail gifting found a functional role in a payment environment shaped by unusual regulatory constraints, and over time both the product infrastructure and the regulatory environment evolved in ways that made that role more stable and more legitimate. The method is unlikely to displace bank-based payments or purpose-built gambling wallets, but the evidence from the regulated market suggests it has secured a durable position for the segment of bettors whose circumstances or preferences it serves particularly well.
Get a Quote

Description

How Gift Cards Became a Trusted Payment Method in US Online Betting, According to Betzonic

The payment landscape for online betting in the United States has shifted considerably over the past decade, shaped by a combination of federal legislation, state-level regulation, and evolving consumer preferences. Among the methods that have carved out a legitimate and growing role in this ecosystem, gift cards stand out as a particularly interesting case. What began as a retail convenience product has evolved into a functional financial instrument that addresses specific friction points in the US online gambling market — friction that stems largely from banking restrictions that have no parallel in most other countries.

The Regulatory Context That Made Gift Cards Relevant

To understand why gift cards gained traction in US online betting, it is necessary to understand the Unlawful Internet Gambling Enforcement Act of 2006, commonly known as UIGEA. This federal law did not make online gambling illegal for players, but it prohibited US banks and payment processors from knowingly accepting transactions related to unlawful online gambling. The practical effect was significant: credit card companies like Visa and Mastercard began declining transactions directed at offshore betting operators, and even many domestic processors adopted conservative blanket policies to avoid compliance risk.

This created a persistent problem for players who wanted to fund accounts legally — particularly after the Supreme Court's 2018 decision in Murphy v. National Collegiate Athletic Association, which struck down the Professional and Amateur Sports Protection Act (PASPA) and opened the door for states to legalize sports betting. As legal, regulated sportsbooks launched in states like New Jersey, Pennsylvania, and Colorado, they still faced the reality that a meaningful percentage of attempted card transactions were declined at the processor level. The gap between legal activity and accessible payment infrastructure became a genuine operational challenge.

Gift cards, particularly those issued on the Visa and Mastercard networks, offered an indirect route around these declines. Because they are purchased at retail locations — grocery stores, pharmacies, convenience stores — the initial transaction is categorized as a retail purchase, not a gambling transaction. When the card is subsequently used at a betting site, the processor sees a prepaid card number rather than a direct bank transfer, which in many cases results in a higher approval rate. This structural characteristic, not any deliberate design for gambling, is what made them practically useful.

How the Gift Card Market Matured to Support Betting Use Cases

The integration of gift cards into online betting did not happen overnight, and it was not driven by the gambling industry alone. The broader prepaid card market in the United States grew substantially between 2010 and 2020, with the Consumer Financial Protection Bureau estimating that Americans loaded over $65 billion onto prepaid cards annually by the mid-2010s. As the infrastructure for these products matured — including better fraud detection, wider retail distribution, and higher load limits — their viability as a payment method for higher-value transactions improved correspondingly.

Several specific product categories became particularly relevant to bettors. Vanilla Visa and Mastercard gift cards, available in denominations up to $500 at most major retailers, became widely used. The OneVanilla and MyVanilla product lines, along with the Neosurf voucher system (which entered the US market from its European base), provided options at different price points and with varying acceptance rates across different operators. Neosurf, in particular, is notable because it was explicitly designed as an anonymous, cash-based voucher for online transactions, which aligned well with the preferences of privacy-conscious bettors.

Operators and review platforms began systematically tracking which gift card products worked at which sites, and which failed. Resources like www.betzonic.com/gift-card-betting-sites/ emerged to document exactly this kind of practical information — which operators accept specific card types, what the deposit limits are, and how the withdrawal process works in conjunction with gift card deposits. This type of aggregated, tested information became genuinely valuable because acceptance was inconsistent and players had no reliable way to know in advance whether a particular card would work at a particular site.

The withdrawal side of the equation remained more complicated. Gift cards are inherently a one-directional instrument — they can receive a load at purchase but cannot receive a bank transfer back from an operator in the way a debit card can. This meant that players using gift cards for deposits typically needed to select a different withdrawal method, most commonly a check by courier, a bank wire, or a cryptocurrency transfer. Operators that catered to gift card users generally developed clear policies around this asymmetry, and it became a standard feature of how the method was presented to customers.

Trust Signals and the Shift Toward Mainstream Acceptance

The question of trust is central to any payment method's adoption curve, and gift cards had specific obstacles to overcome in the betting context. Early use of prepaid cards in online gambling was associated with offshore, unlicensed operators, which created a reputational association that took years to reverse. As state-regulated markets expanded — by 2023, legal sports betting was available in more than 30 US states — the operators within those markets were subject to licensing requirements, responsible gambling mandates, and financial auditing that fundamentally changed the nature of the transaction.

Licensed operators in states like Michigan, Illinois, and Virginia had to meet strict requirements from their respective gaming control boards, including standards for payment processing transparency and anti-money laundering compliance. Accepting gift cards within this framework required operators to implement controls around maximum deposit limits, identity verification thresholds, and transaction monitoring. The result was that gift card use at licensed sites became a documented, auditable activity rather than an anonymous workaround — which paradoxically increased its legitimacy even while reducing some of the privacy characteristics that had originally attracted certain users.

Betzonic, which has tracked payment method developments across the US regulated market, has noted that the number of licensed operators explicitly advertising gift card acceptance grew substantially between 2020 and 2024. This visibility shift is meaningful: operators that list gift cards as an accepted method in their banking pages are making a deliberate commercial decision, not simply tolerating an edge case. It signals that the method has reached a sufficient volume of user demand to justify the compliance infrastructure required to support it properly.

Consumer trust was also reinforced by the dispute resolution mechanisms that came with regulated environments. A player using a gift card at a licensed New Jersey sportsbook, for example, had access to the Division of Gaming Enforcement as a regulatory backstop if a deposit was processed incorrectly or funds were disputed. This was categorically different from the situation facing players at offshore sites, where no such recourse existed. The combination of state licensing and consumer protection frameworks transformed the risk profile of gift card betting transactions in a way that made broader adoption rational rather than merely convenient.

Current Patterns and Practical Considerations for Users

As of the mid-2020s, gift card use in US online betting reflects a relatively stable set of patterns. The method is most commonly used by players who do not have a credit card that will process gambling transactions successfully, who prefer to manage their betting budget through a discrete, fixed-amount instrument, or who have privacy preferences that make direct bank connections unattractive. It is not a dominant payment method by transaction volume — ACH transfers, PayPal, and Play+ prepaid accounts hold larger shares at most major operators — but it occupies a consistent and identifiable niche.

Acceptance rates vary considerably by operator and by card product. Visa and Mastercard network gift cards tend to have higher acceptance rates at US-licensed sites than store-branded or single-retailer gift cards, which are generally not accepted for betting deposits at all. The denomination of the card can also affect processing: some operators apply different verification requirements to transactions above certain thresholds, which can complicate the use of higher-value cards. Players who use this method regularly typically develop practical knowledge about which specific products work reliably at their preferred operators, and this experiential knowledge is often shared in betting communities and review platforms.

Fees are a genuine consideration that is sometimes underweighted in discussions of gift card convenience. Most network-branded gift cards carry a purchase fee of $3.95 to $6.95 depending on the denomination and the retail outlet. For a $100 deposit, a $5.95 activation fee represents a 5.95% transaction cost — higher than most other payment methods available at licensed US sportsbooks. Players who use gift cards as a primary deposit method absorb these costs as a premium for the specific characteristics the method provides, whether that is privacy, budget control, or simply reliable transaction approval.

The trajectory of gift cards as a payment method in US online betting is ultimately a story about market adaptation. A product designed for retail gifting found a functional role in a payment environment shaped by unusual regulatory constraints, and over time both the product infrastructure and the regulatory environment evolved in ways that made that role more stable and more legitimate. The method is unlikely to displace bank-based payments or purpose-built gambling wallets, but the evidence from the regulated market suggests it has secured a durable position for the segment of bettors whose circumstances or preferences it serves particularly well.
Copyright All A's Events 2024
Translate »